Where Are We In Terms Of The Global Financial Situation?

Happy Birthday, Global Financial Crisis

First Published: ADawnJournal.com September 24, 2009

There has been so much said over the past couple of years about the dangers of recession, and much still to be said, but one event seen by many as the moment that the global financial crisis became a fact was the collapse of the American investment bank Lehman Brothers. It was one year ago this week that the bank went bust, and the realities of the crisis became clear to everyone at that point. If the Global Financial Crisis has a birthday, that date is the 16th of September. One year on, where are we in terms of the global financial situation?

The collapse of Lehman Brothers marked the point where governments around the world decided that intervention was the way to go. From that point on, many banks have been effectively nationalised – an act which in itself was massively controversial, seeing diverse reactions in different countries. In America, for example, Barack Obama’s determination to bolster the banking sector and revive the world’s largest economy led to accusations of totalitarianism, communism and Nazism. It may sound amusing, but this reaction was, seemingly, entirely serious. In other nations, a sense of skepticism over bank bailouts also persisted, but the bailouts are ratified now and the recovery is in place.

Would the world’s economy have bounced back in such a way and so soon without the government interventions that took place in most of the larger economies? It seems unlikely. Certainly, the banks which have received bailout cash have posted mixed results, with Goldman Sachs posting record numbers very shortly after receiving their lifeline, while others have suffered record losses. But many independent sources feel that the recession is in its last blasts and that this is due in no small part to government intervention. No government has given any indication that further bailout cash will be released, however, so it is now very much a matter of waiting for the situation to stabilise.

While we wait for that, it is believed that the recession has yet to do the last of its work in the sphere of employment. A recent report from the OECD claims that as many as 15million people worldwide have lost their jobs as a result of the financial crisis, and that there could yet be another 10million people made unemployed. Although economic results are improving, the effects of the recession will still be felt for a while to come.

While it would be fair to say that the financial sector has always had its critics, the overwhelming thread running through public reaction to the situation has been one of severe distrust of banks and bankers, and of injustice at the bailouts given to banks while many other industries have been left to fend for themselves. There is still a reluctance on the part of the banks to lend to customers – much to the chagrin of the governments which released the cash to save them – and it might be a while before the stability being claimed for the global economy is seen in the bank accounts and employment prospects of the “man on the street”. This story has some time to run as it blows out the solitary candle on its birthday cake.
Scam Alert - Beware of This Canada Revenue Agency Letter

Sample CRA scams

Scam Alert - Beware of This Canada Revenue Agency Letter

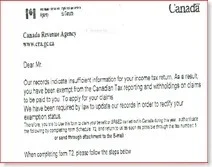
Canada Revenue Agency recently issued a warning asking taxpayers to beware of a scam letter asking Canadians for personal information. CRA has not sent any such letters asking for any personal information whatsoever. Be extremely careful when you receive this type of mail. Feel free to view the attached picture of this scam letter.

This letter claims that there is "insufficient information" for your tax return and you have to update your records to receive any claims. It does not stop here. There is an attached form asking to fax or email your personal information. This letter is not from CRA. You should be vigilant when anyone (even CRA) asking you to release personal information. If you ever receive any such letters asking personal information, call the institution to verify first. Visit CRA Web site for more info.

If you ever believe you have been a victim or someone has tried to scam you, here is what you can do:

- Call your local RCMP detachment or your Police Department

- Report your situation online through Reporting Economic Crime Online

- Visit PhoneBusters, send an email to info@phonebusters.com, or call 1-888-495-8501

Remember, common sense and vigilance are your best defence.

Qantas International Business Class Review | Auckland – Sydney | Boeing 737-800 (winglets)

New Zealand Travel Blog: Part 17 | QANTAS Business Class | Boeing 737 - 800

Business Class | Boeing 737 - 800

Like my Business Class flight from Melbourne to Auckland, I was expecting a business class cabin suite like in the Airbus A330 - 200, but I was disappointed. Qantas 737 - 800 Business Class seats are just upgraded versions of economy class.

These are not lie-flat seats. Laid out in a 2-2 configuration, Qantas 737 - 800 seats are recliner seats wrapped in maroon leather which offers 37 inches pitch and 22 inches width. There is no direct aisle access for window-side passengers. 

 Seats have an adjustable headrest and there is a 10.6-inch entertainment screen in the back of the seat. The problem with this is if the front person reclines, your monitor reclines too. For 7 inches more legroom and 5 inches more width, if I were paying for this flight, I would not upgrade from economy. 

The food, however, I couldn’t complain about. I had a sourdough sandwich with roast beef, cheddar cheese, tomato, and baby spinach. I also had coffee, ice cream and orange juice.

 The washrooms were OK, but I have had better ones in other business class flights. Another thing I noticed was that the aisle was narrow, so it was not easy to walk to the washroom if you bump into another person.

Overall, my experience with Qantas 737 - 800 was average. I was missing my Melbourne – Auckland Airbus A330 – 200 trip the whole time.

 I was scheduled to reach Sydney at 8:05 PM and planned to take the subway to reach my hotel in downtown Sydney. It would probably be midnight by the time I got there and I was excited about the experience of taking the subway in Sydney for the first time.

Should You Take Out A Second Mortgage?

Second Mortgages

There will no doubt be a lot of people who, on hearing of the idea of a second mortgage, will ask rhetorically “With all the problems that a first mortgage seems to create, who on earth would wish to take out a second?". And while the question is understandable, the fact is that a number of people need to take out a second mortgage, while others who know that they can make the payments will take out a second mortgage to aid their cash flow for a large scale purchase for which their first mortgage and their deposit do not quite make up enough capital. The second mortgage should not be a first resort, but an option in the background when other options are frustrated.

A second mortgage is a common solution when a borrower has found the house of their dreams, and with the financing they have so far managed to secure they are unable to meet the asking price. Taking out a second mortgage – for a smaller amount than the first, naturally – may be the best option. The second mortgage is not, however, usually taken out so soon after the first, not least because the first mortgage in such a case is normally taken for the fullest amount the borrower can get. A second mortgage is frequently used in order to raise the money for repairs on an existing property or for some other necessary expense. They are usually given at a higher interest rate than the first mortgage, and begin to be paid off only once the first mortgage has been cleared in full.

For many of the above reasons, a second mortgage is something of a last resort in times of either dire need or acute want. If the property you are hoping to secure has immense resale potential and simply requires that last bit of financing to make it yours, then there is clear reason to look for the second mortgage. This should only be done, however, if you have exhausted other options, principally going to the lender who gave you the first mortgage and asking them if they can increase the amount of the loan. In doing this, you keep the loan at the original rate of interest and maintain the term of the loan. It may well mean paying off more per month, but there are points of negotiation.

Similar to the above, yet marginally different, is the refinancing of your mortgage. By extending the term of your first mortgage you can free up more cash for whatever you need, and maintain monthly payments at a reasonable level. You may also be able to use equity in your existing home. If you have owed the home for a significant period of time, especially if you have made improvements to it, then there may have been an increase in the value of the property, allowing you to place this equity into your first mortgage. It will increase the term of the loan and you will need to ensure that the interest rate is the same before proceeding. However, as compared to a second loan, it will usually be a better idea.