Scam Alert - Beware of This Canada Revenue Agency Letter

Sample CRA scams

Scam Alert - Beware of This Canada Revenue Agency Letter

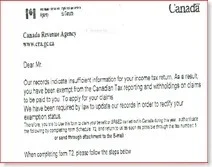
Canada Revenue Agency recently issued a warning asking taxpayers to beware of a scam letter asking Canadians for personal information. CRA has not sent any such letters asking for any personal information whatsoever. Be extremely careful when you receive this type of mail. Feel free to view the attached picture of this scam letter.

This letter claims that there is "insufficient information" for your tax return and you have to update your records to receive any claims. It does not stop here. There is an attached form asking to fax or email your personal information. This letter is not from CRA. You should be vigilant when anyone (even CRA) asking you to release personal information. If you ever receive any such letters asking personal information, call the institution to verify first. Visit CRA Web site for more info.

If you ever believe you have been a victim or someone has tried to scam you, here is what you can do:

- Call your local RCMP detachment or your Police Department

- Report your situation online through Reporting Economic Crime Online

- Visit PhoneBusters, send an email to info@phonebusters.com, or call 1-888-495-8501

Remember, common sense and vigilance are your best defence.

Qantas International Business Class Review | Auckland – Sydney | Boeing 737-800 (winglets)

New Zealand Travel Blog: Part 17 | QANTAS Business Class | Boeing 737 - 800

Business Class | Boeing 737 - 800

Like my Business Class flight from Melbourne to Auckland, I was expecting a business class cabin suite like in the Airbus A330 - 200, but I was disappointed. Qantas 737 - 800 Business Class seats are just upgraded versions of economy class.

These are not lie-flat seats. Laid out in a 2-2 configuration, Qantas 737 - 800 seats are recliner seats wrapped in maroon leather which offers 37 inches pitch and 22 inches width. There is no direct aisle access for window-side passengers. 

 Seats have an adjustable headrest and there is a 10.6-inch entertainment screen in the back of the seat. The problem with this is if the front person reclines, your monitor reclines too. For 7 inches more legroom and 5 inches more width, if I were paying for this flight, I would not upgrade from economy. 

The food, however, I couldn’t complain about. I had a sourdough sandwich with roast beef, cheddar cheese, tomato, and baby spinach. I also had coffee, ice cream and orange juice.

 The washrooms were OK, but I have had better ones in other business class flights. Another thing I noticed was that the aisle was narrow, so it was not easy to walk to the washroom if you bump into another person.

Overall, my experience with Qantas 737 - 800 was average. I was missing my Melbourne – Auckland Airbus A330 – 200 trip the whole time.

 I was scheduled to reach Sydney at 8:05 PM and planned to take the subway to reach my hotel in downtown Sydney. It would probably be midnight by the time I got there and I was excited about the experience of taking the subway in Sydney for the first time.

Should You Take Out A Second Mortgage?

Second Mortgages

There will no doubt be a lot of people who, on hearing of the idea of a second mortgage, will ask rhetorically “With all the problems that a first mortgage seems to create, who on earth would wish to take out a second?". And while the question is understandable, the fact is that a number of people need to take out a second mortgage, while others who know that they can make the payments will take out a second mortgage to aid their cash flow for a large scale purchase for which their first mortgage and their deposit do not quite make up enough capital. The second mortgage should not be a first resort, but an option in the background when other options are frustrated.

A second mortgage is a common solution when a borrower has found the house of their dreams, and with the financing they have so far managed to secure they are unable to meet the asking price. Taking out a second mortgage – for a smaller amount than the first, naturally – may be the best option. The second mortgage is not, however, usually taken out so soon after the first, not least because the first mortgage in such a case is normally taken for the fullest amount the borrower can get. A second mortgage is frequently used in order to raise the money for repairs on an existing property or for some other necessary expense. They are usually given at a higher interest rate than the first mortgage, and begin to be paid off only once the first mortgage has been cleared in full.

For many of the above reasons, a second mortgage is something of a last resort in times of either dire need or acute want. If the property you are hoping to secure has immense resale potential and simply requires that last bit of financing to make it yours, then there is clear reason to look for the second mortgage. This should only be done, however, if you have exhausted other options, principally going to the lender who gave you the first mortgage and asking them if they can increase the amount of the loan. In doing this, you keep the loan at the original rate of interest and maintain the term of the loan. It may well mean paying off more per month, but there are points of negotiation.

Similar to the above, yet marginally different, is the refinancing of your mortgage. By extending the term of your first mortgage you can free up more cash for whatever you need, and maintain monthly payments at a reasonable level. You may also be able to use equity in your existing home. If you have owed the home for a significant period of time, especially if you have made improvements to it, then there may have been an increase in the value of the property, allowing you to place this equity into your first mortgage. It will increase the term of the loan and you will need to ensure that the interest rate is the same before proceeding. However, as compared to a second loan, it will usually be a better idea.

The Day I Knew Invest Now Changed Someone’s Life

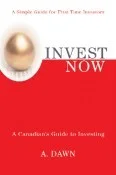
Invest Now: A Canadian’s Guide to Investing

When I was writing Invest Now, I was often occupied with the idea  that the objective of this book would be to change someone’s life. I was not too worried about selling lots of copies, or making lots of money, or even becoming a famous author. I was worried about only one thing. My target was something very simple and straight forward - to change a one person’s life. To help someone with what I have learned all these years, and to enlighten someone’s life with all of the knowledge and hard work I put into my first book. If I accomplish this, I would consider Invest Now a successful venture, and I would consider myself content with the feeling of joy and accomplishment.

And then came the day I had been waiting for. This is what I have wanted to happen since Invest Now was published. On the weekend of July 12, 2008, I was attending a community-based book fair and cultural festival. This event was taking place at the Church of St Columba & All Hallows, 2723 St. Clair Avenue East, Toronto. On Sunday, July 13, some visitors were browsing Invest Now. Some of them were just passing by after having a quick glance at my stall. All of a sudden, a guy rushed to my stall out of nowhere. His first question was, “Are you the author of Invest Now”? I replied, “Yes.” Then what he told me went beyond my imagination. I was totally astonished – but my heart was filled with indescribable joy and a sense of accomplishment. I am now going to share with you what that gentleman told me.

He works as a financial advisor. He came across Invest Now at a local bookstore. At first, he bought one copy for himself out of curiosity. And then, he fell in love with Invest Now instantly. He was having a hard time explaining the world of investments to his clients. Once he found Invest Now, he started giving a copy to his clients. So far, he has distributed 7 or 8 copies, but it did not stop there - he started recommending Invest Now to other advisors at his firm. He also wrote a few articles in the local newspaper, and he recommended Invest Now in those articles. Finally he said, “Thank you, thank you so much for writing a book like this, and helping lots of people to understand such a complex matter in easy way. It saved me so much time and work – before I would spend days explaining investments to my clients; now I give them this book and ask them to read it first before I recommend anything else. You made my life so easy – I appreciate your hard work and thank you for helping so many people.”

It definitely feels good knowing Invest Now has served its purpose, and changed someone’s life. I am sure I will come across many more stories like this in the years to come. However, this is not where everything ends. This is just the beginning. With my website “A Dawn Journal”, and with more books to be published in the future – I will be able to change many others’ lives. I will be able to help a lot more people; that’s what makes me write more. I needed a confidence boost, and this reader just gave me that. What I heard from him was exactly what I needed to be confident in continuing my journey into the future.